⚠️ Attention: BUSINESS OWNERS, INVESTORS, AND W2-PROFESSIONALS ... EARNING $300k+
Discover The Same Private Wealth Structure Nine-Figure Families Have Used For Over A Century To Legally Reduce Your Taxes, Protect Your Assets, Create More Cashflow, And Pass Down A Legacy — For Generations Without Stress or Confusion...
🎥 Press Play - Watch The PFO Blueprint Workshop
If your income has grown but your taxes, exposure, complexity and financial obligations seem to grow right along with it, there is a reason.
And making more money by itself will not fix it.
For Qualified Business Owners, Executives, Investors & High-Earning w2-Professionals
Includes The PFO Blueprint, Private PFO Briefing, Resources, Community Access, PFO Profile & Assessment Session
JD — W-2 Professional
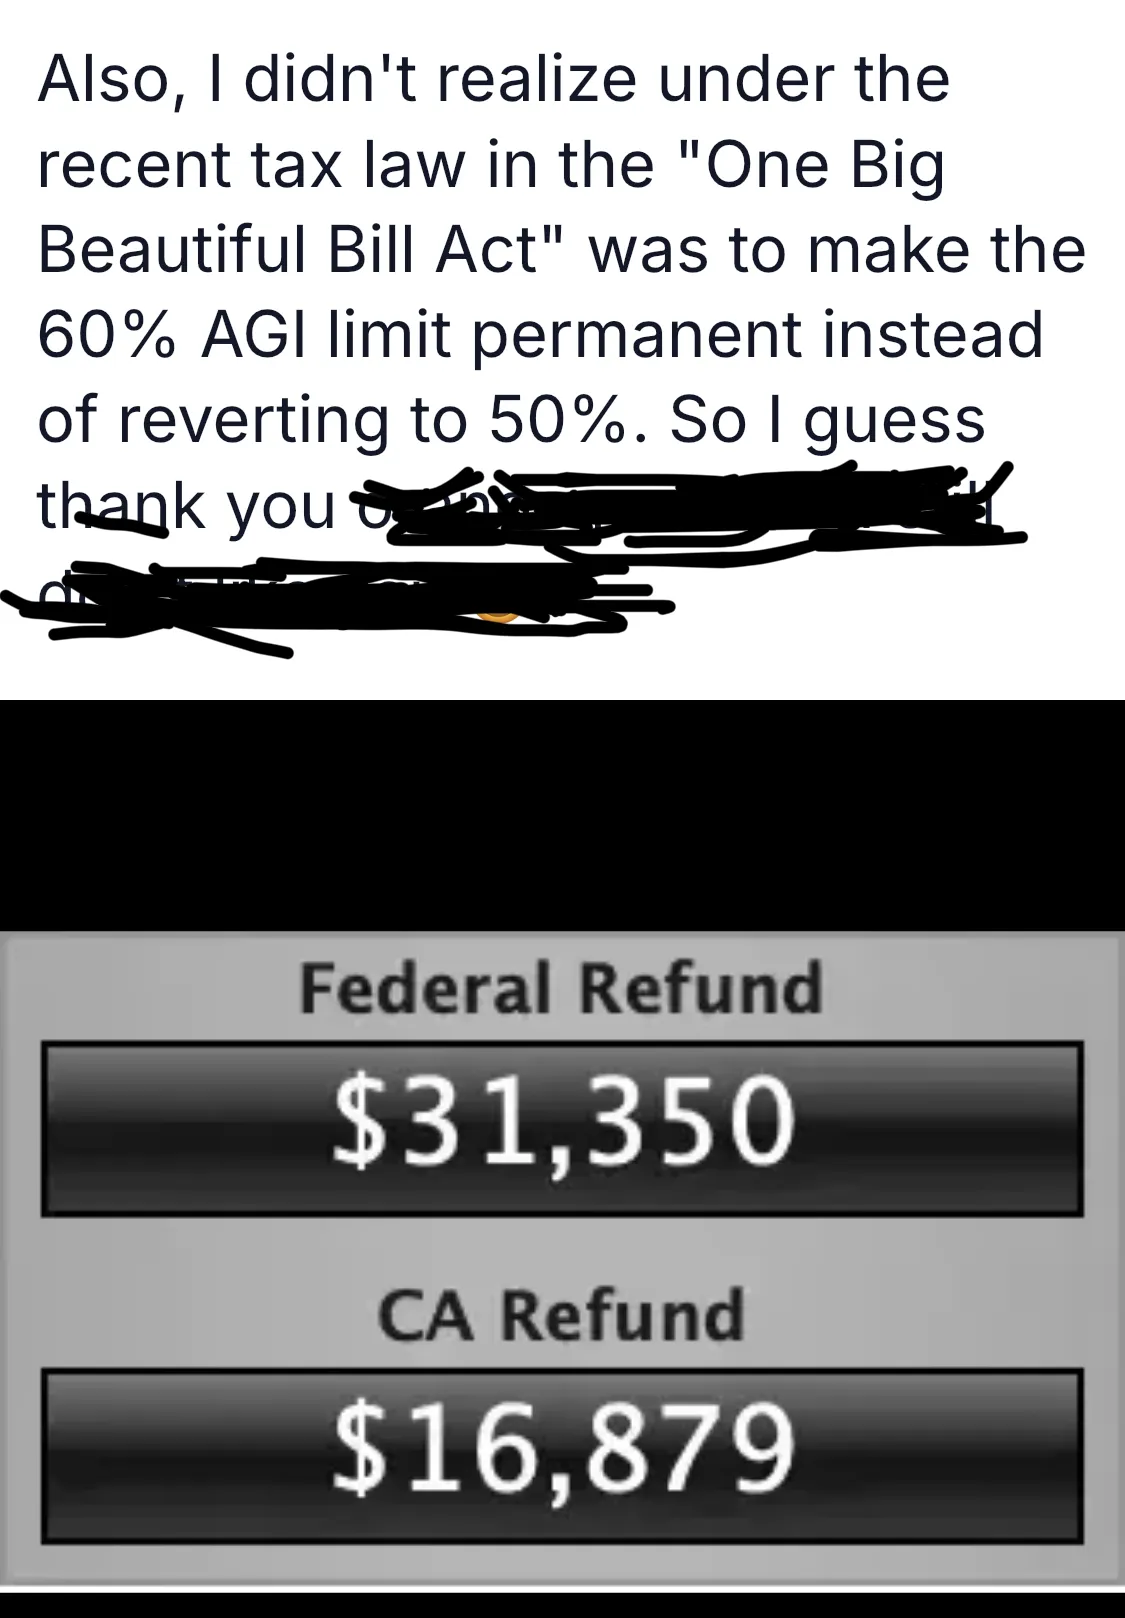
Was facing a $13,000 federal tax bill. After restructuring: $31,000 refund.
"This is a no-brainer."
Melanie — W-2 Professional
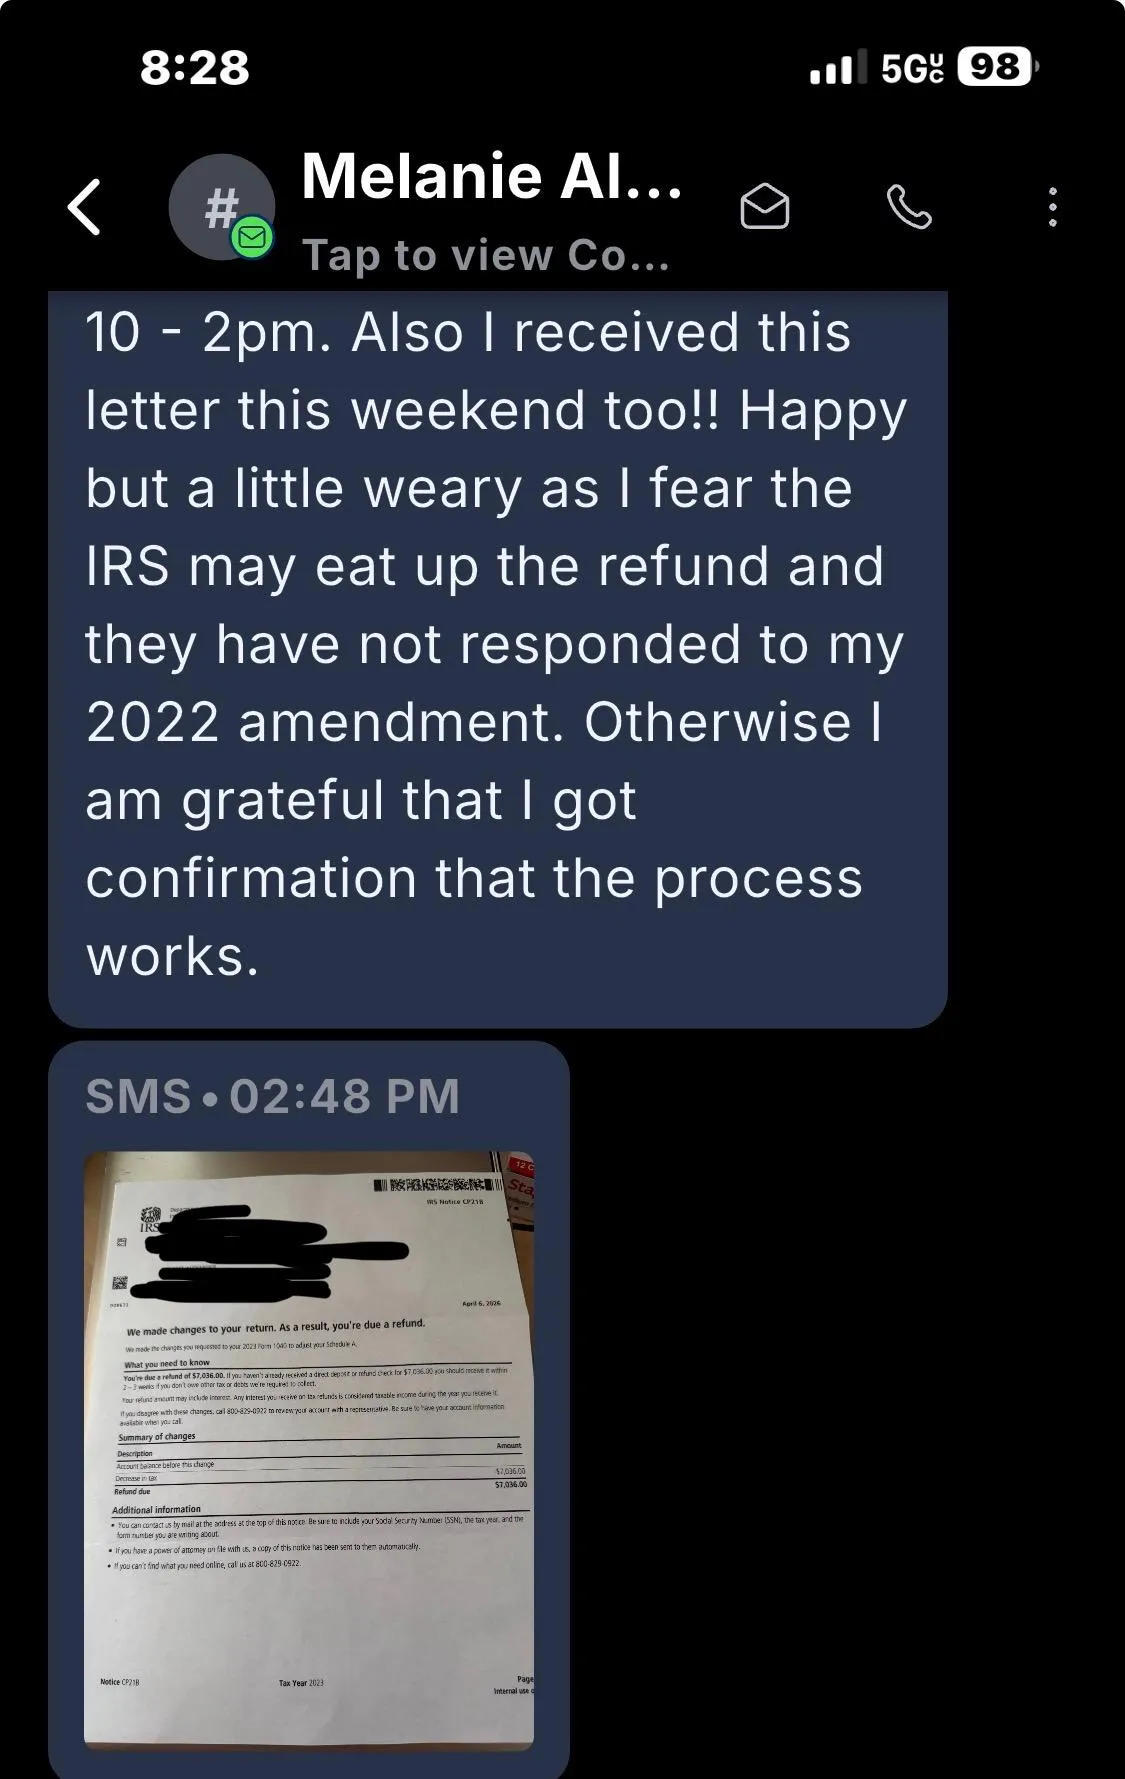
Came in owing $20,000 in taxes. After restructuring: received a $7,000 refund. A $27,000 swing in one cycle.
Dr Ramos — Dr & Investor
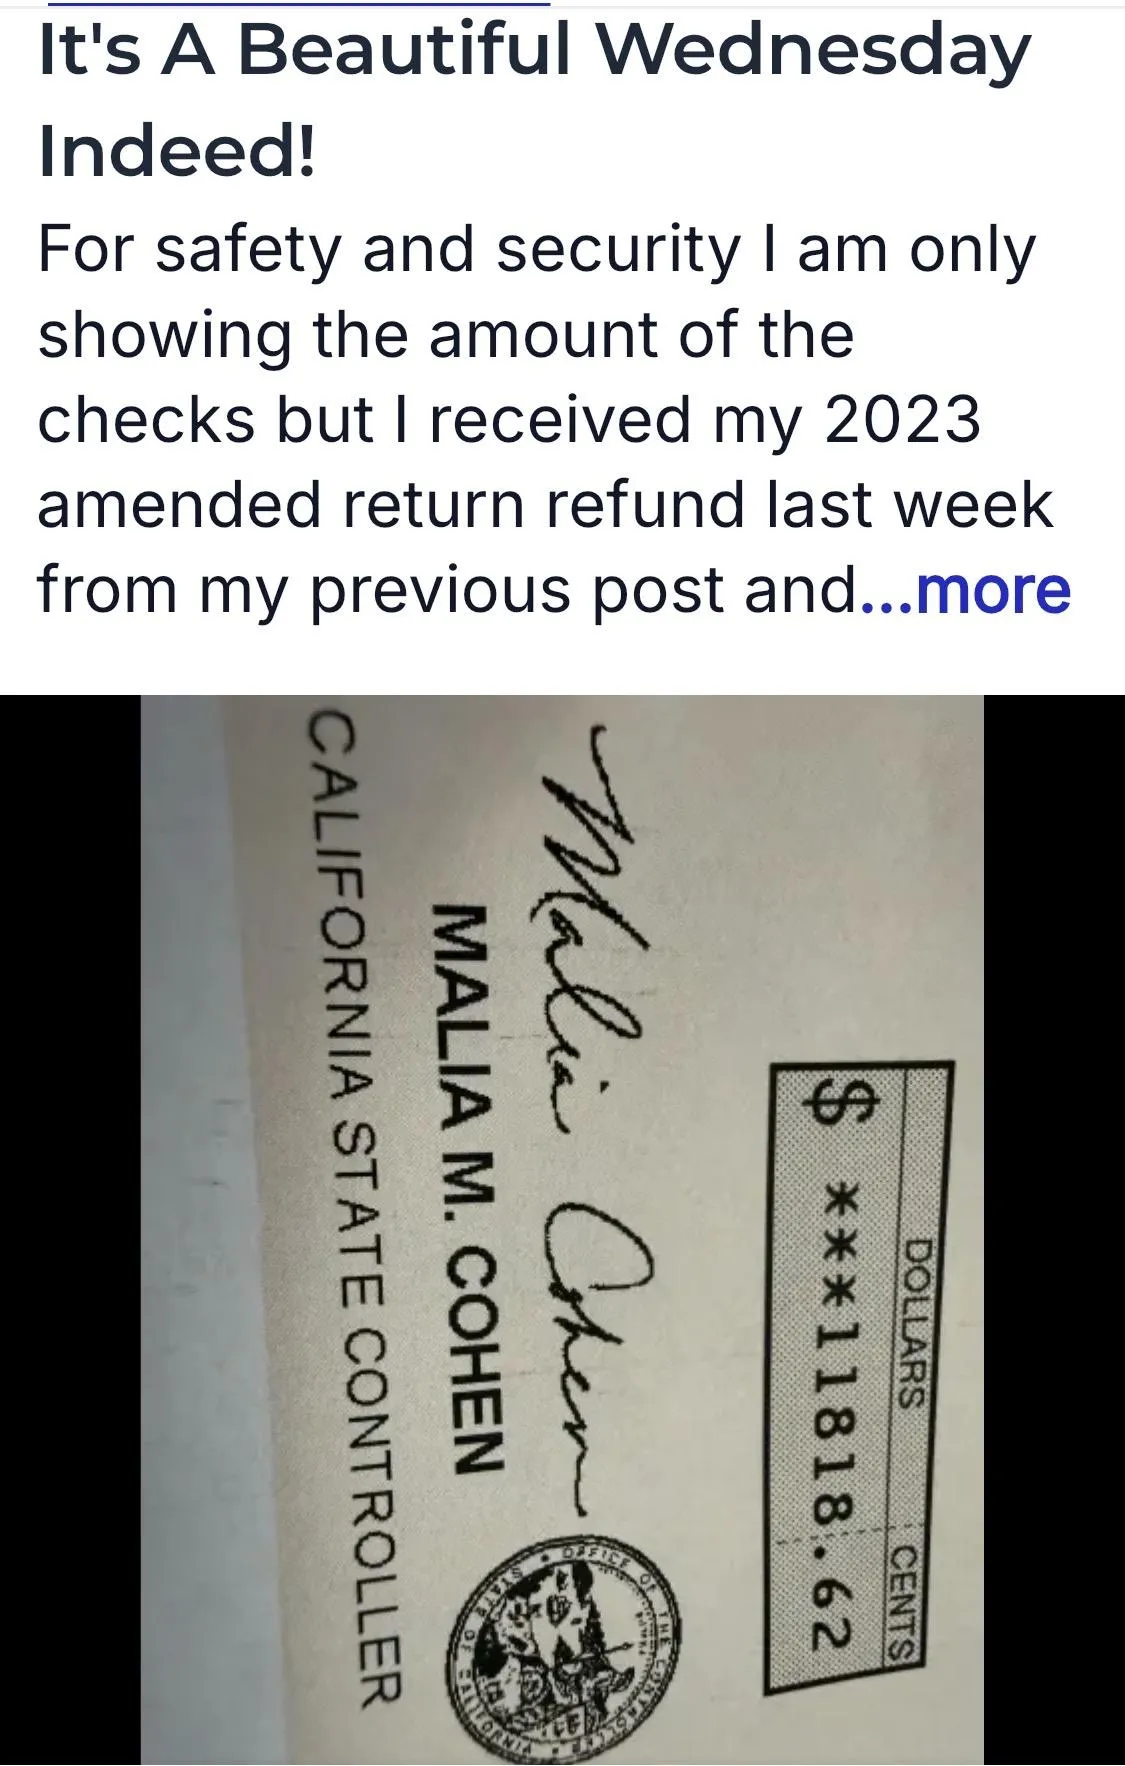
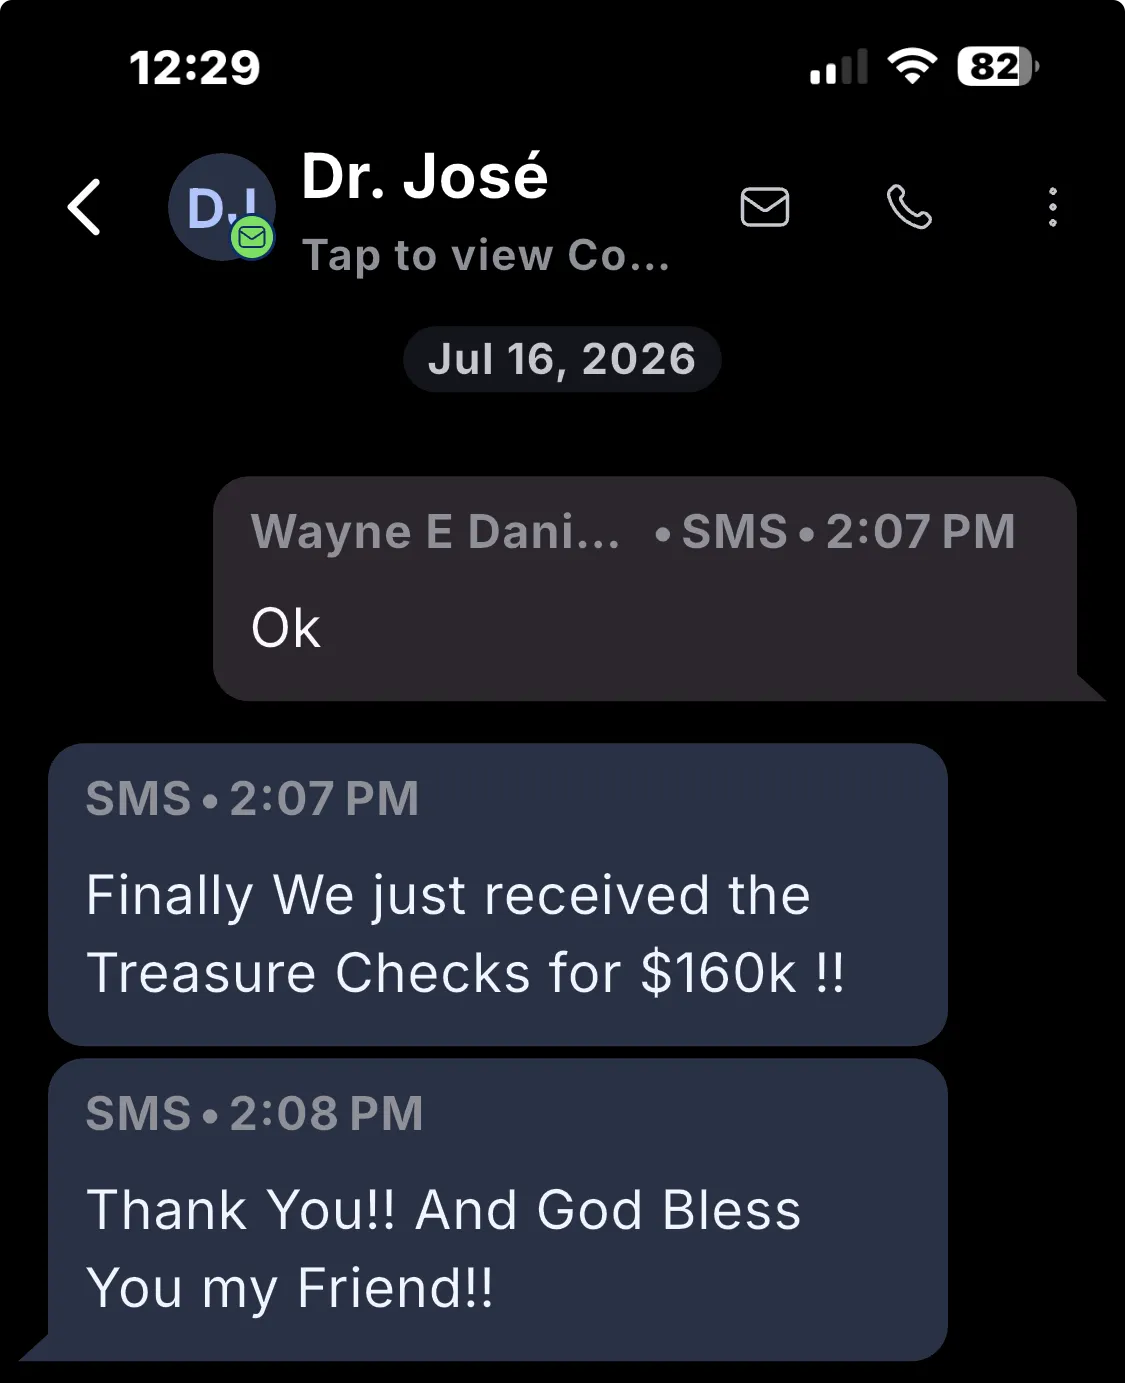
Amended prior two years — $160,000 recovered.
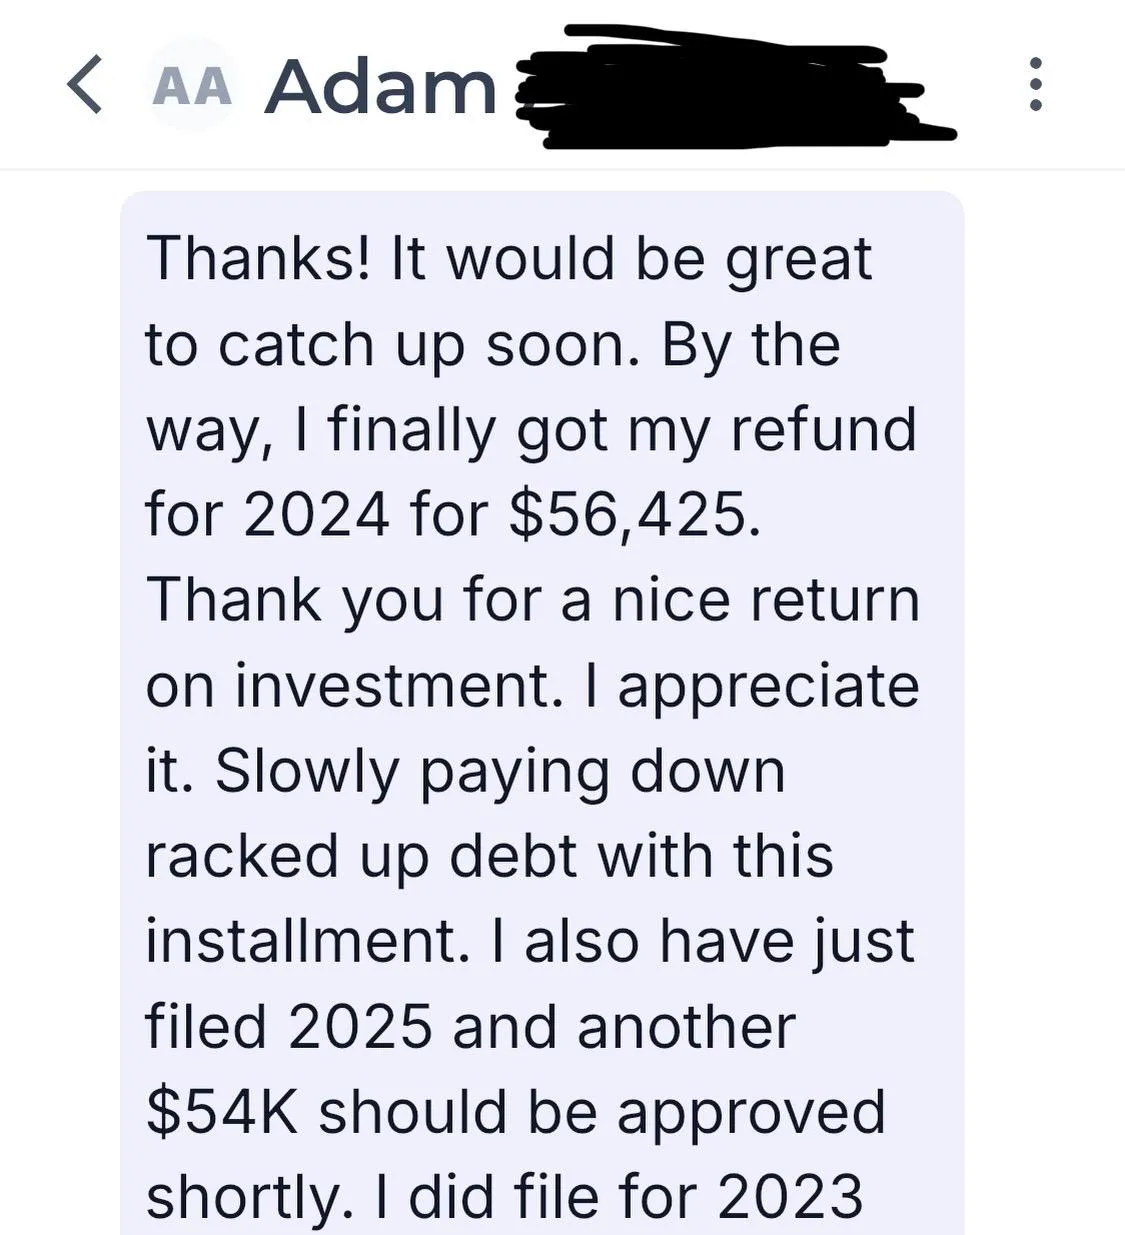
Adam — Marketer
$110,000 returned in 8 weeks.
"The greatest return on investment I've ever made."
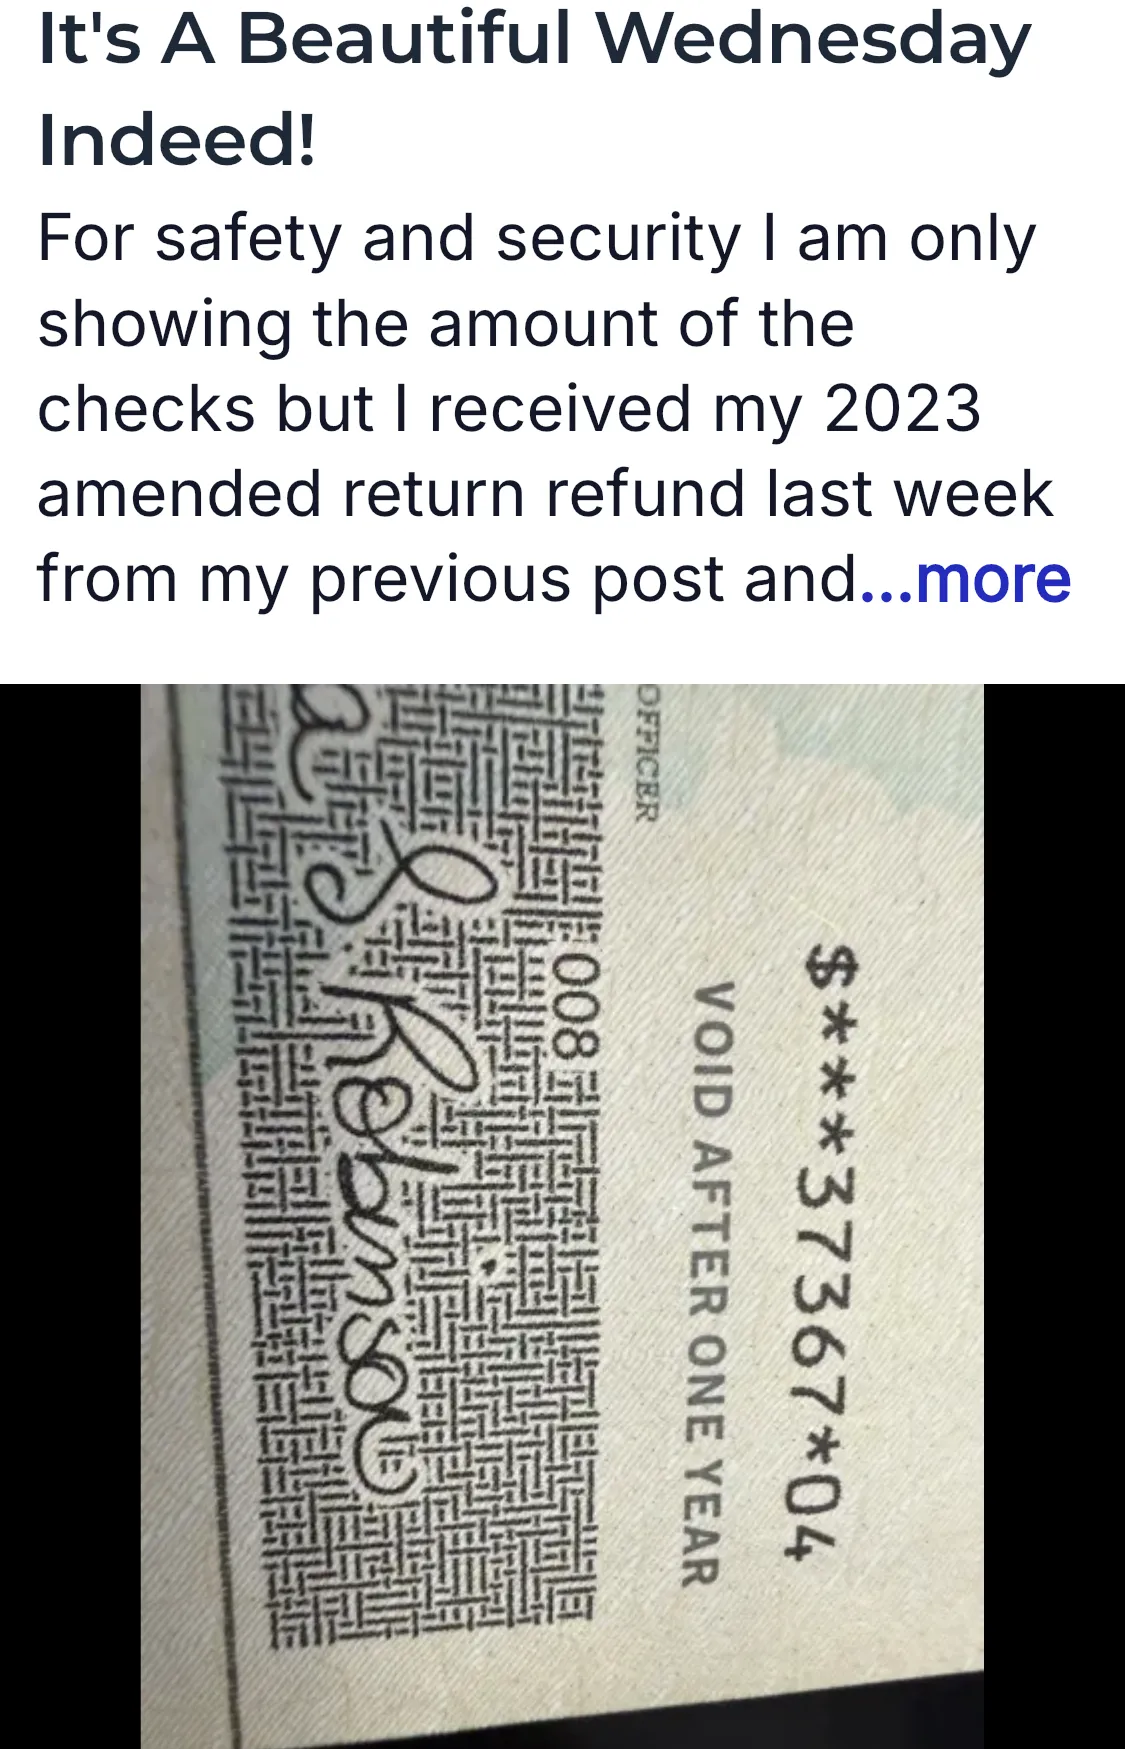
JD — W-2 Professional
Amended prior two years — $37,367 recovered. Over $150,000 total in four months.
There Comes A Point Where Making More Money Stops Solving The Problem...
At the beginning, the financial game is fairly simple.
You need more money.
So you work harder.
Build something.
Sell something.
Get promoted.
Invest.
Take risks.
Start businesses.
Buy properties.
Create opportunities.
And if you are reading this, there is a good chance you became very good at it.
You figured out how to produce.
But eventually something changes.
Your income goes up, and your taxes go up.
Your assets increase, and your exposure increases.
Your businesses grow, and your complexity grows.
You hire more advisors.
Open more accounts.
Create more entities.
Buy more insurance.
Sign more documents.
Acquire more assets.
And somehow, even though you are objectively doing better than ever before, more people seem to have a claim on the money you produce.
That is the part almost nobody prepares high earners for.
Because once you become successful, your primary financial problem begins shifting from:
"How do I make more money?"
to:
"How much of the money I already make is actually becoming permanent family wealth?"
Those are entirely different games.
And most successful people continue playing the first one for years after they should have learned the second.
The "Default" Gets Paid Before Your Family Does
That sounds contradictory until you understand the difference between income and retained capital.
Imagine you unnecessarily lose $50,000 this year.
You still make plenty of money.
Your lifestyle does not change.
Your business remains profitable.
Your investments remain healthy.
So emotionally, nothing feels wrong.
But that $50,000 had a future.
It could have purchased another asset.
It could have funded another business.
It could have been invested.
It could have produced income.
It could have compounded.
It could have increased liquidity.
It could have created options.
It could eventually have passed to your children.
So losing $50,000 today does not simply cost you $50,000.
It costs you whatever that $50,000 could have become.
And then you repeat the process next year.
And the next year.
And the next.
At $50,000 per year, that is $250,000 across five years before considering growth.
$500,000 across ten.
$1 million across twenty.
And that is just one of the leaks.
Now imagine the cumulative effect of taxes, bad ownership decisions, missed planning opportunities, poorly timed transactions, unnecessary exposure and capital that could have been structured differently across an entire financial lifetime.
That number is almost impossible to calculate.
Which is exactly why most people never calculate it.
They simply absorb the loss and keep earning.
High income has an amazing ability to hide financial inefficiency.
You can lose an extraordinary amount of money while still feeling successful.
For Qualified Business Owners, Executives, Investors & High-Earning w2-Professionals
Includes The PFO Blueprint, Private PFO Briefing, Resources, Community Access, PFO Profile & Assessment Session
I Went From Losing 3 Million To Building A Personal Family Office™ By Rejecting The Default Financial Wisdom And Rebuilding Everything Around Control, Protection, And Growth
This Is Something Completely New, Completely Different, Completely Unlike Anything You've Ever Heard of or Seen Before - Apply Now To Discover The PFO Effect
Dear Future PFO Owner,
From: The desk of Wayne Daniels, Jr.
Re: If You Make Over $300K+, This Is For You
Surprised to see a $197 price tag on access to a framework that could put millions back in your pockets and change how you think about taxes, asset protection, privacy, and long-term control?
I thought you might be.
Would it surprise you even more to learn that I have helped hundreds of entrepreneurs, business owners, and high-earning professionals uncover a completely different way to structure wealth, keep more of what they earn, and stop leaving everything tied directly to their personal name?
Skeptical?

You should be.
Because you cannot believe everything you read on the internet. 😃
So let me show you why this is different.
But first, read this carefully:
I have the benefit of more than 20 years and over $250,000 invested in researching law, finance, trust law, contract law, banking codes, and constitutional framework. I have tested what I teach against real-world scrutiny, and I have a retired 30-year IRS Criminal Investigator on my team who has reviewed the strategies and confirms the legitimacy of the structure.
The average person who signs up for "how to" information gets little to no result because information alone changes nothing. So this isn't that. This is not a DIY program offer or course. This is an opportunity to see the Personal Family Office in full. Then if you decide to move forward with me, we'll build and install it together. So, if you are looking for magic, shortcuts, or something to save you without requiring any shift from you, this is not for you.
And yes, it took me two decades, a quarter of a million dollars, losing everything twice, and rebuilding from nothing to see what I am about to show you.
But once I saw it, everything changed.
Because I finally understood something most high earners never realize until it is far too late:
Making money does not automatically make you free.
If you are still being taxed without control, you are not free.
If your assets can still be reached, you are not free.
If everything you own is still tied directly to your name, you are not free.
If your life can be tracked, traced, and exposed through the same default structures everyone else uses, you are not free.
That is why the PFO matters.
Because money is freedom. Time is freedom. Privacy is freedom. And control is freedom.
And once you understand how to structure wealth around those principles, you stop seeing taxes, ownership, asset protection, and legacy the way everyone else does.
With that said, let me show you what changed everything for me...
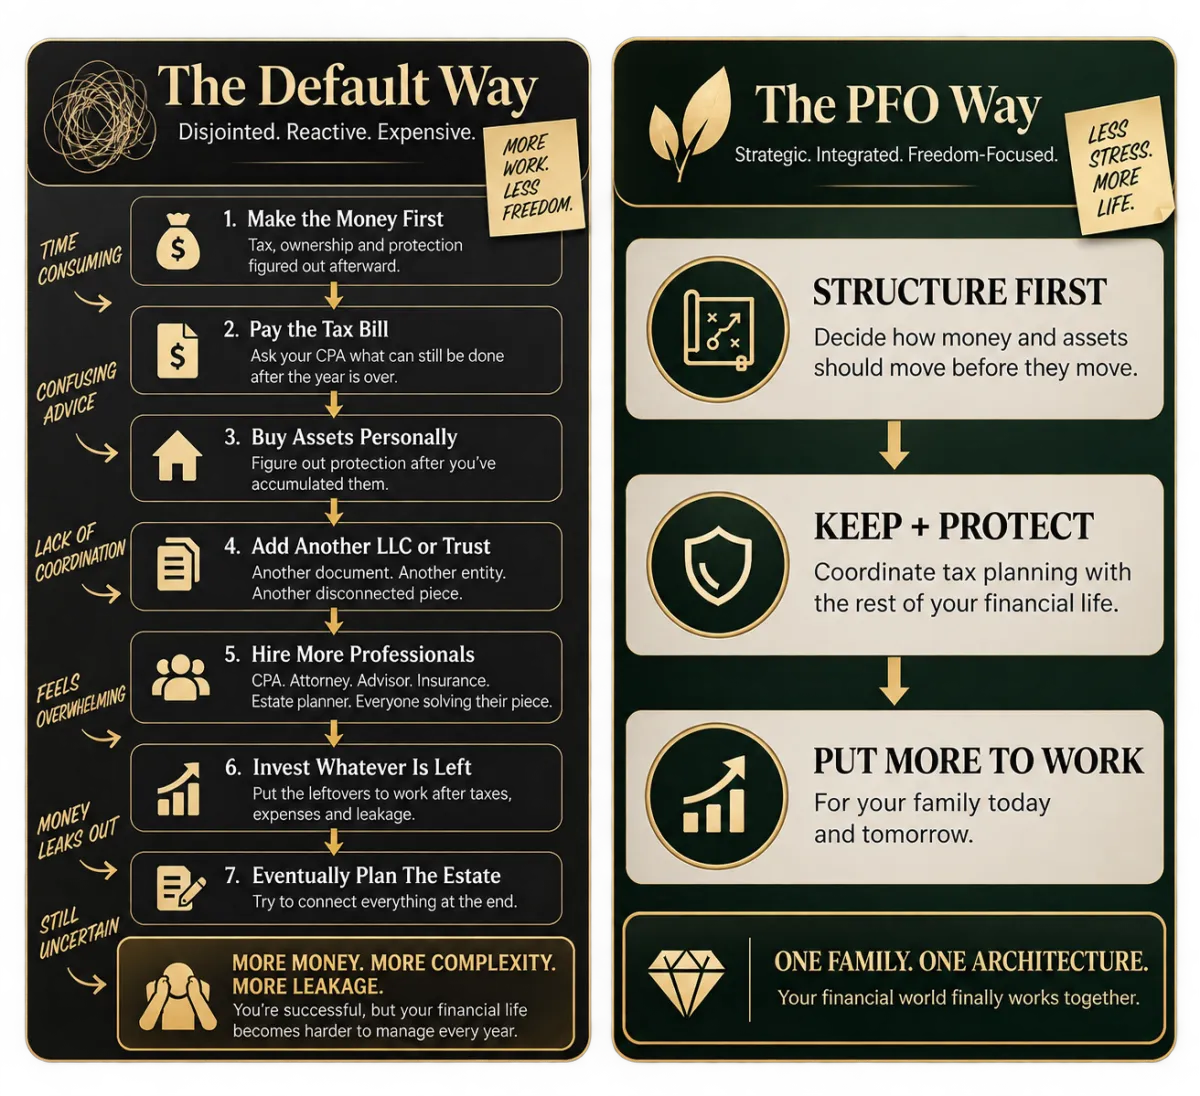
You Can Continue To Do Things The Default Way or The PFO Way...
For Qualified Business Owners, Executives, Investors & High-Earning w2-Professionals
Includes The PFO Blueprint, Private PFO Briefing, Resources, Community Access, PFO Profile & Assessment Session
Which is Why You Can Make Great Money While Still Losing Wealth Every Year...
Think about the normal financial sequence...
You produce the income.
Taxes get paid first.
Interest gets paid.
Fees get paid.
Business expenses get paid.
Insurance premiums get paid.
Advisors get paid.
Banks make their spread.
Investment companies collect their fees.
Everybody performs the role they are supposed to perform.
And then your family gets whatever is left over after everything you worked for got picked apart.
That arrangement is so normal that most people never think to question it.
You earn.
Everyone gets paid.
You try to save and invest the leftovers.
And then you go work more to make more.
That may work when the numbers are small.
But once you are moving $300,000, $500,000, $1 million or several million dollars a year, percentages that once seemed insignificant begin representing serious capital losses.
And now something strange happens.
The better you become at producing money, the more money the default has access to.
Now, your success feeds the machine.
That does not mean anyone is intentionally doing anything wrong.
Your accountant can be excellent at what they do.
Your attorney can be excellent in what they do.
Your investment advisor can be excellent.
Your banker can be excellent.
The problem is that each of them is typically responsible for their small piece.
And they are all operating excellently, just in the DEFAULT...
Nobody is automatically responsible for asking:
"How do we structure this entire financial life so the greatest reasonable amount of capital stays inside this family, remains protected, continues growing, and eventually transfers according to this family's wishes?"
That responsibility falls back on you.
And most people were never taught how to do it.
And That Is Where The Trap Is
Because when successful people feel financial pressure, what do they normally do?
They make more.
Another client.
Another investment.
Another property.
Another deal.
Another product.
Another promotion.
Another business.
Another million.
We become obsessed with increasing the top of the funnel while rarely stopping to ask how much is disappearing through the bottom.
That only works until you realize something.
There may be more economic value hiding inside the money you already make than inside the next dollar you are chasing.
Because recovering or retaining $100,000 does not require another sale.
It does not require another employee.
It does not require another property.
It does not require another promotion.
It does not require another hour away from your family.
You already produced the money.
The question is whether you have built an intelligent enough system around yourself to keep it working for you.
That is where the entire conversation changes.
Taxes Are Usually The First Place Successful People Feel It...
Taxes are obvious because you can see them.
You see the check.
You see the withdrawal.
You see the number on the return.
And when you are paying $75,000, $150,000, $250,000, $500,000 or more, eventually you start wondering whether there is another way to think about the problem.
Could planning have started sooner?
Were opportunities missed?
Could transactions have been structured differently?
Could prior filings contain legitimate recovery opportunities?
Is the current business structure still appropriate?
Are you making major tax decisions before the event happens or merely reporting what happened afterward?
Those are worthwhile questions.
But here is where things get interesting.
Suppose you successfully KEEP another $100,000.
Now what?
The game changes dramatically...
Where does that capital go?
How should it be held?
What should own it?
How should it be protected?
How should it be invested?
How does it interact with your business?
What about your estate plan?
Your children?
Your charitable goals?
Your succession strategy?
Suddenly the tax problem has revealed an ownership problem.
Solve the ownership problem and you discover the protection problem.
Solve the protection problem and you create an investment problem because now there is more capital to deploy.
Grow that capital and eventually you create a transfer problem.
One problem opens the door to the next.
That is why the wealthiest and financially savvy families eventually stop solving financial problems individually.
They build private architecture.
For Qualified Business Owners, Executives, Investors & High-Earning w2-Professionals
Includes The PFO Blueprint, Private PFO Briefing, Resources, Community Access, PFO Profile & Assessment Session
That Is Why Family Offices Exist
The wealthiest families learned this lesson generations ago.
Once enough wealth exists, managing it as a series of unrelated financial transactions becomes inefficient.
So they created family offices.
The family office puts the family at the center of the financial architecture.
Taxes connect to ownership.
Ownership connects to protection.
Protection connects to investment.
Investment connects to estate planning.
Estate planning connects to succession.
Philanthropy connects to family values.
Major decisions are considered in relation to the entire family enterprise instead of being solved in isolation.
Traditionally, this level of coordination has belonged to families worth $100 million, $500 million or several billion dollars because hiring an entire team of attorneys, accountants, investment professionals, administrators and specialists for one family is expensive.
But there is a giant problem nobody talks about enough.
You can experience many of the same financial problems long before you have $100 million.
You can earn $500,000 per year and have serious tax problems.
You can own $3 million of assets and have serious protection problems.
You can own multiple businesses and have serious ownership problems.
You can have children and immediately have transfer problems.
You can have trusts, entities, retirement accounts, insurance, investments, real estate and multiple professionals and already have coordination problems.
You can have enough complexity to need family-office thinking without having enough wealth to justify employing an entire traditional family office.
That is the gap.
Enter The Personal Family Office
A Personal Family Office is designed to bring family-office thinking, architecture and coordination to successful families whose financial lives have outgrown ordinary household planning.
You do not need a $500 million balance sheet.
You need enough financial activity that continuing to operate by default has become expensive.
And the simplest way we think about that process is through five stages:
RECOVER → KEEP → PROTECT → GROW → TRANSFER
First, RECOVER.
Where legitimate opportunities exist to recover capital from previous years, previous planning or missed opportunities, identify them.
Then KEEP.
Before obsessing over another return, determine how much more of the money you already produce can reasonably stay inside your family's financial ecosystem.
Then PROTECT.
Because accumulating wealth while leaving important assets unnecessarily exposed creates another problem.
Then GROW.
Now retained and protected capital can be deployed intelligently into investments, businesses, real estate and other opportunities appropriate for the family.
Then TRANSFER.
Because wealth that disappears when you do is simply accumulated money.
Generational wealth requires architecture capable of carrying assets, responsibility and intention beyond you.
That sequence changes how you look at almost every financial decision.
The Wealthiest Number In Your Financial Life May Be One You Have Never Calculated
Everybody knows their income.
Most successful people know their net worth.
Some know their investment returns.
Almost nobody knows this number:
How much wealth would your family have today if you had retained every dollar you could have reasonably retained, protected it properly, and compounded it intelligently for the last ten years?
Think about that.
You probably cannot calculate it precisely.
But you already know the answer is not zero.
There were decisions you did not know to make.
Strategies you learned too late.
Assets purchased before you understood ownership.
Tax years that closed before anyone looked backward.
Transactions that happened before planning happened.
Money you earned once and then lost forever.
That is history.
You cannot change every decision behind you.
But you can decide what happens to the next ten years.
Because Time Works For You Or Against You
This is where waiting becomes expensive.
Most people think waiting is neutral.
"I'll deal with this next year."
"I'll look into the trust later."
"I'll handle protection when we have more assets."
"I'll figure out the tax strategy before we sell."
"I'll update the estate plan eventually."
But time is never neutral around money.
Another year passes.
Another tax year closes.
Another transaction happens.
Another asset is purchased.
Another $50,000 or $100,000 potentially leaves.
Another year of potential compounding disappears with it.
And some financial decisions become dramatically harder to change after the event occurs.
Tax planning is generally more powerful before the transaction.
Asset protection is generally more useful before the threat.
Succession planning is easier before succession becomes necessary.
Estate planning works better while everyone responsible for the decisions is alive, healthy and capable of making them.
Financial architecture gives you the most options when you build it before you desperately need it.
That is why the right time to begin is rarely "someday."
Someday usually arrives after something bad has already happened and now you're in reaction mode.
For Qualified Business Owners, Executives, Investors & High-Earning w2-Professionals
Includes The PFO Blueprint, Private PFO Briefing, Resources, Community Access, PFO Profile & Assessment Session
There Is A Difference Between Having Money And Having Financial Control
Money buys things.
Control creates choices...
The house is nice.
The car is nice.
The travel is nice.
The watches, boats, memberships and experiences can all be enjoyable.
But the deeper luxury is knowing your financial life has been deliberately designed.
Knowing why assets are owned the way they are owned.
Knowing where capital should flow before it arrives.
Knowing your family is thinking about taxes before tax season.
Knowing important assets are being evaluated for protection before trouble appears.
Knowing additional retained capital has a purpose.
Knowing your estate plan is part of a larger transfer strategy rather than a binder sitting somewhere waiting for you to die.
Knowing your children are inheriting more than assets.
They are inheriting architecture.
That is a different level of financial maturity.
It is the point where the family stops simply being successful and starts operating like an dynasty.
And We Have Seen How Valuable That Shift Can Become
In one client situation, more than $250,000 was recovered, including approximately $160,000 connected to one year, with roughly $65,000 in ongoing annual savings based on that family's circumstances.
Another client recovered approximately $200,000 and identified roughly $50,000 per year in ongoing savings.
Another recovered approximately $155,000, with approximately $70,000 per year in projected ongoing savings based on their situation.
We have also seen situations where ownership and protection became particularly important once litigation entered the picture.
And we have worked around major business transactions where timing, structure, taxation and reinvestment could materially affect what the family ultimately retained.
Those are only a few of the individual outcomes based on their specific situation and circumstances.
They are not promises of what will happen for you because your situation may be different...
But they demonstrate why these questions matter.
When significant money is moving through your life, small structural differences can become very large financial differences over time.
So The Question Is No Longer Whether You Can Make Money
You already answered that.
The question is whether the financial system surrounding that money is worthy of what you have built.
Does it help you RECOVER?
Does it help you KEEP?
Does it help you PROTECT?
Does it help you GROW?
Does it help you TRANSFER?
Or are you still operating under a collection of defaults you inherited when your financial life was much smaller?
That distinction matters.
Because your family may have outgrown the system years ago.
You simply never had language for the problem.
The PFO Blueprint + Assessment Call
If you are reading this and thinking, "I need somebody to look at my situation," that is exactly why we created the PFO Blueprint + Assessment Call.
This is not a generic consultation call.
And it is not a "pick your brain" call either.
It is a private easy to follow walkthrough and assessment process for successful families seriously considering Personal Family Office implementation.
The purpose is to help you understand where your current financial architecture may deserve attention, identify the areas that appear most important to investigate, and determine whether building a Personal Family Office makes sense for your situation.
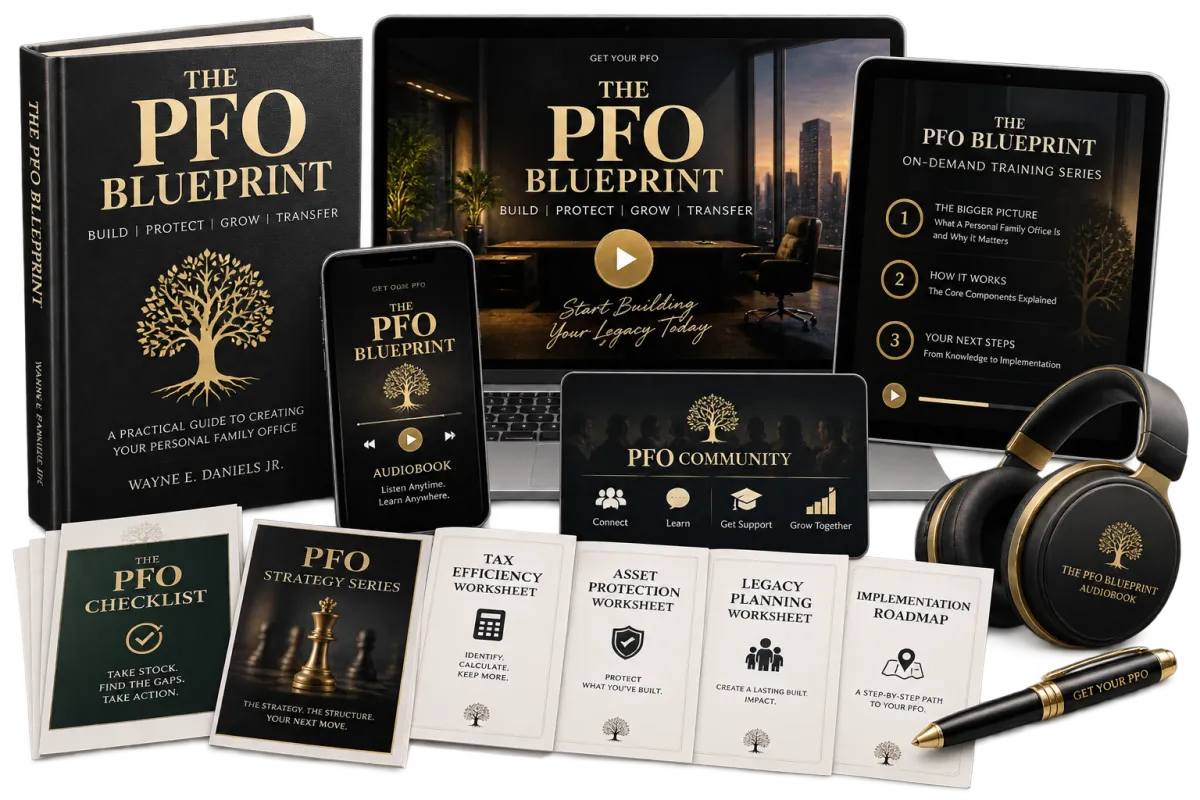
Your $197 PFO Blueprint + Assessment call also includes:
• The PFO Blueprint book and core framework
• The PFO Strategy Briefing
• Supporting PFO resource materials
• Access to the growing PFO community
• Your PFO Profile and Assessment process
• A private PFO Assessnent Session with me
The materials included help prepare you to understand the framework.
The PFO profile gives us context around your situation...
And the private session allows us to discuss where you are now, what you are trying to accomplish, where potential gaps may exist, and whether there is enough opportunity to justify moving forward.
For Qualified Business Owners, Executives, Investors & High-Earning w2-Professionals
Includes The PFO Blueprint, Private PFO Briefing, Resources, Community Access, PFO Profile & Assessment Session
Why $197?
Because information is cheap.
But paying attention is not.
My private calendar is intentionally limited, and I want those conversations reserved for people who are actively looking for a plug-and-play solution.
Someone who wants to learn about Personal Family Offices can get the PFO Blueprint - read the book and watch the educational material.
Someone who wants to ask interesting questions can ask them inside the community chat on our live weekly Q & A...
And the Private PFO Blueprint + Assessment Call is for the person who has reached a different point.
You already know something needs to change.
You are looking for the right architecture.
You are willing to examine your numbers.
And if the right solution is in front of you, you are capable of implementing it.
So the $197 is a commitment threshold.
It protects your time.
It protects mine.
And it allows us to spend our private time talking about your situation instead of starting at square one.
Who Should Get Access...
This process tends to make the most sense for business owners, executives, investors and high-income professionals generally earning $300,000 or more annually who pay a lot in taxes taxes, has meaningful business interests, investments, real estate, assets, estate concerns or family responsibilities and who recognize that their financial life has become too consequential to continue operating in the default.
You do not need to know exactly what is wrong.
That is part of what we investigate.
But you should already know that continuing to do the same thing for another five or ten years is not an acceptable strategy.
Who This Is (And Isn't) For
This IS for you if you are:
Still handing 30-40% of your income to the IRS every year, this is for you.
A business owner earning $250K, $500K, even $1M+, who is tired of building success in a structure that keeps bleeding them.
An executive who finally reached the title, the salary, and the status, only to realize they still do not control enough of what they earn.
A doctor, dentist, attorney, or consultant who can create immense value for others, but still has too much of their own income, assets, and risk tied directly to them.
An investor who can grow capital, spot opportunity, and make smart moves, but still watches too much of the upside disappear before it reaches their future.
A parent who did everything right, built the income, made the sacrifices, and still knows the structure around their wealth is too fragile for the life they are trying to protect.
Someone who looks successful from the outside, but knows deep down they do not yet have the control, protection, or ownership their wealth should have created.
If that is you, the answer is not to work harder inside the same system. It is to restructure how your wealth is held, protected, and passed on. That is what the PFO Blueprint™ is built to help you do.
This is NOT for you if:
You earn under $200K/year (this structure becomes powerful at higher income levels)
You're looking for a get-rich-quick scheme or an illegal tax dodge
You want a DIY kit to build this yourself (this is built correctly by professionals or it doesn't work)
You're not willing to look at your financial life from a completely different perspective
You need everything to fit inside what your CPA already told you
With a Personal Family Office™, you:
→ Stop being the direct point of risk for everything you build
→ Reduce unnecessary tax exposure by restructuring how income is received and classified — not by chasing deductions inside the same broken system
→ Gain real control over your capital — where it flows, how it's held, and who benefits from it
→ Create a legacy structure designed to transfer intact for generations — without probate, without estate taxes, and without the system taking its final cut
→ Join a private community of hundreds of professionals who have already made this shift and can confirm every word of what you just read
What Happens If We Discover A PFO Makes Sense?
Then we will talk about what implementation looks like for you.
Full Personal Family Office implementation is a significant professional engagement.
Depending on complexity and the level of implementation support required, families who work with us typically invest approximately $21,000 to $36,000.
And I'm sharing this number with you here intentionally.
I do not want you surprised on a private call...
In fact, I HATE doing sales calls. There's nothing I'd rather do less than twist peoples arms to get them to give me their money...
If investing at that level to lower or eliminate yearly tax bills, correct ownership issues that makes you vulnerable and exposed, stet up bulletproof asset protection, exponentially grow capital and generational wealth would be completely unreasonable for you, then the Assessment is probably premature at this time.
But if you are already thinking about what the next five, ten or twenty years of financial default will cost you if you do nothing, then you understand the other side of that equation.
The cost of solving a serious financial problem matters.
So does the cost of leaving it unsolved.
Because "Doing Nothing" Is Still A Financial Decision
If nothing changes, something still happens...
Another year goes by.
More money comes in.
More money goes out.
More assets accumulate.
More exposure accumulates.
More decisions get made.
More opportunities either get captured or missed.
And eventually the next ten years look a lot like the last ten.
That may be perfectly acceptable.
But if something in you already knows there is a better way to operate, pay attention to that.
You do not need another decade of lose to get more evidence.
You need to find out what the gap actually is and close it ASAP!
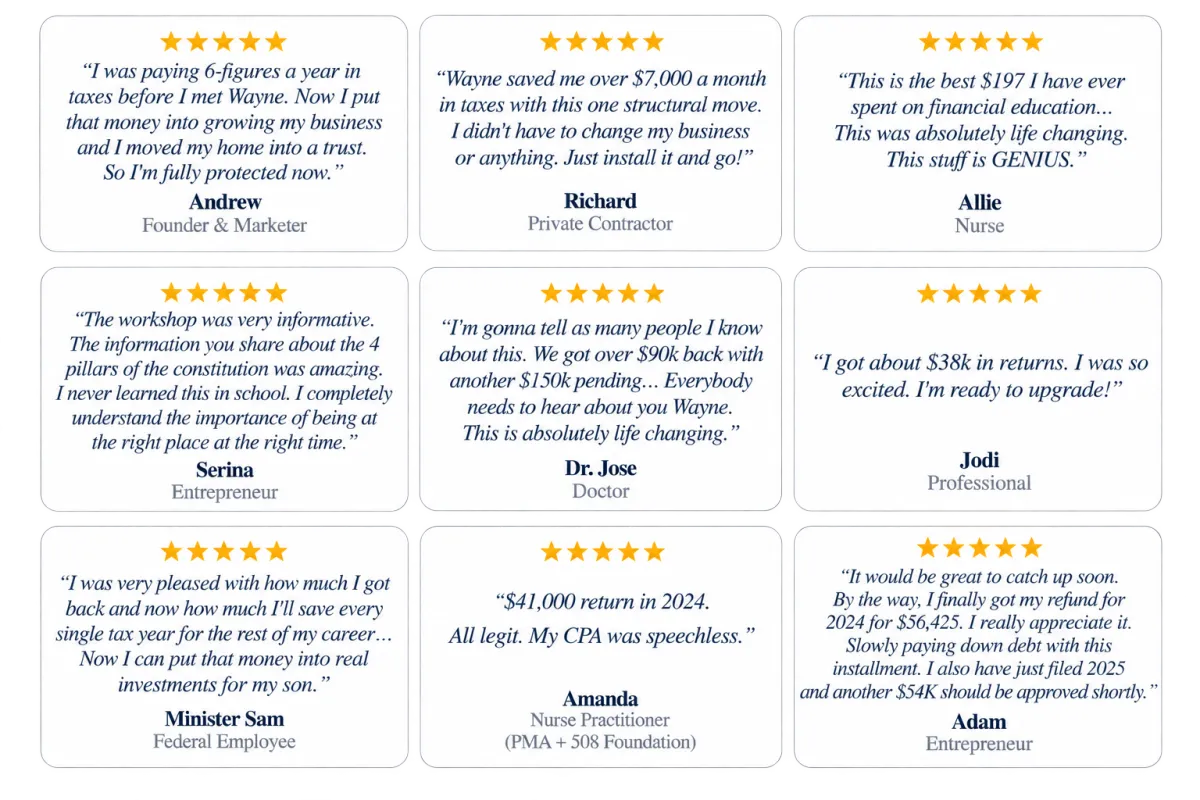
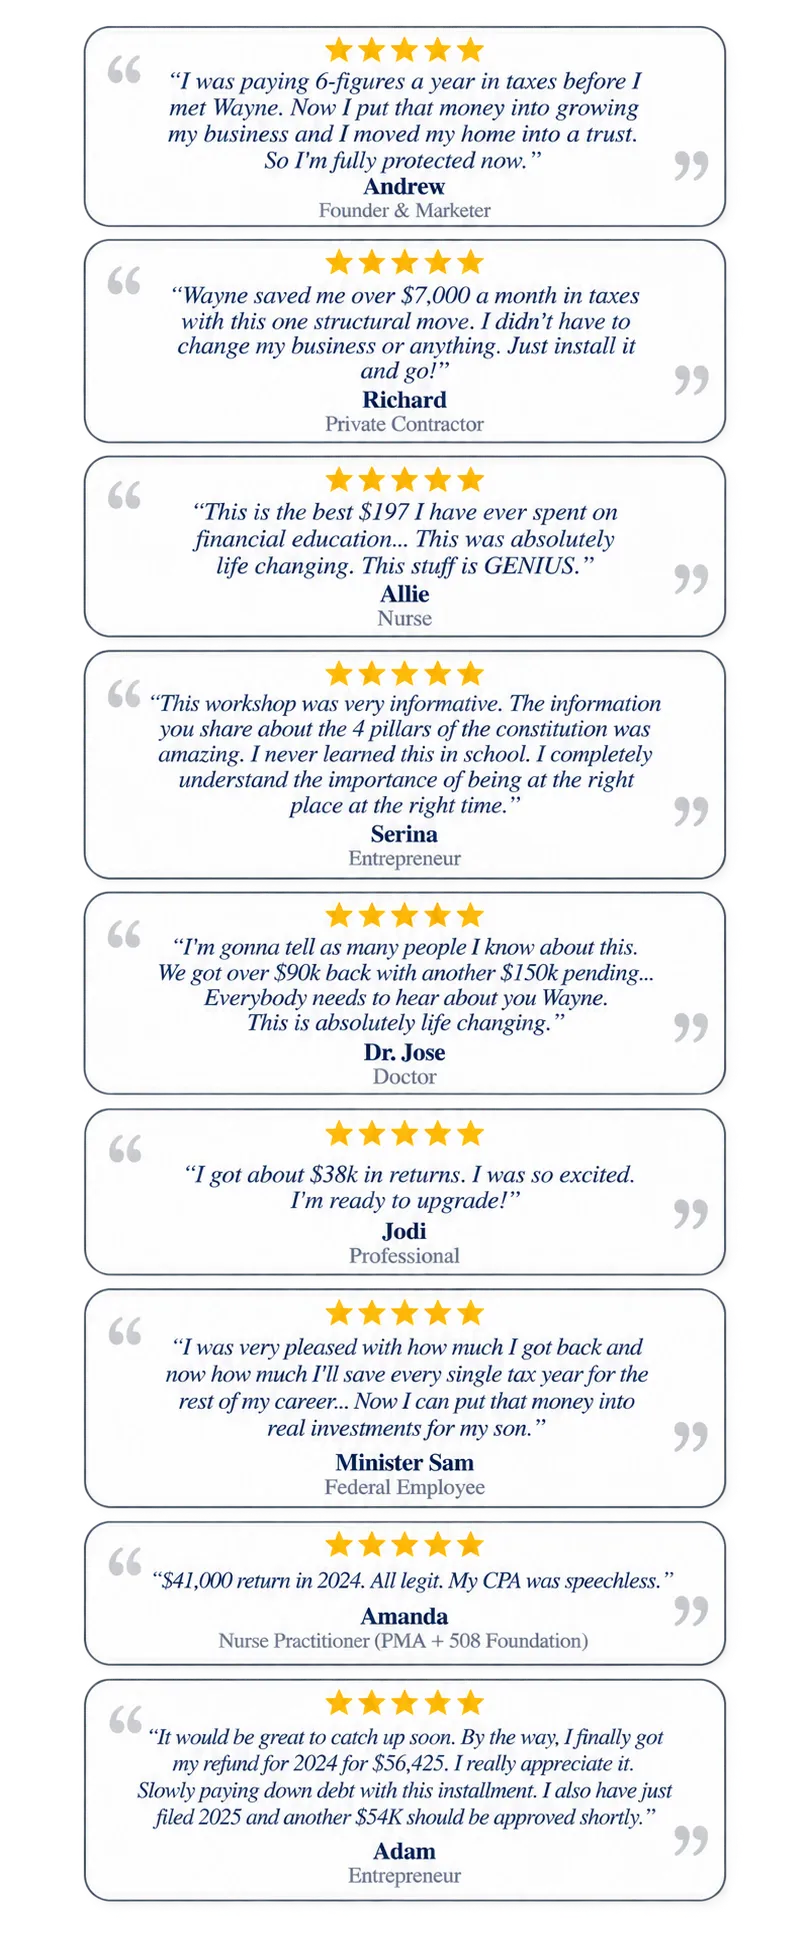
These are just a few of the hundreds of professionals and business owners who have made this shift. Inside the community, you can ask them directly. You don't need to take our word for it.
INSIDE THE PFO BLUEPRINT™
$197 One-time payment. Instant digital access. No subscription. No hidden fees.
Includes The PFO Blueprint, Private PFO Briefing, Resources, Community Access, PFO Profile & Assessment Session
Full PFO Implementation Typically Ranges From Approximately $21,000 To $36,000
You Have Already Proven You Can Create Wealth.
Now Build The Structure That Helps Your Family Keep It.
Recover what you can.
Keep more of what you create.
Protect what you have accumulated.
Grow the capital you keep.
Transfer it intentionally.
And stop allowing a financial default designed for a much simpler life to determine what happens to the wealth you are building now.
If your family has reached that point, get the PFO Blueprint & Assessment.
So There's One Final Question
If nothing about your current financial structure changed for the next ten years, but your income continued growing...
Would that excite you?
Or would you immediately start thinking about how much more money would flow through the same system?
That is the question.
Because making more money through the same financial architecture does not automatically create more financial control.
Sometimes it simply gives the existing system more money to work with.
At some point, the architecture has to change.
And if you suspect you have reached that point, the next move is to find out.
Buy Back Your Freedom. Buy Back Your Future.
At this level you are likely working 4 to 5 months every year just to satisfy taxes.
From January through April, sometimes even May, too much of what you earn is going somewhere other than your future.
A Personal Family Office™ helps flip that equation.
You reclaim more of your time. You direct more of your money. You decide what your wealth is built to do.
Because when your income and assets are structured the right way, more of what you earn can stay aligned with your family instead of leaking through the default system. It can compound with greater control, protection, and purpose.
This is not just about saving money. It is about reclaiming your life and stepping into a future where more of your effort finally works for you.
What does that feel like a year from now, knowing you bought back your time, your future, and a level of freedom most people never realize they lost?
One-time payment. Instant digital access. No subscription. No hidden fees.
The Real Cost Is Not The Seat. The Cost Is Delay.
For someone in your position $197 is not a life altering decision.
The decision is whether you are ready to stop letting the wrong structure cost you far more than that every single year.
This seat gives you access to the blueprint and the assessment.
And If you move forward with us, it is credited toward your Personal Family Office™.
If you do not, you still walk away with a clearer understanding of how to protect more of what you earn, how to create more separation, and how to think like the families who keep wealth for generations.
Either way, the value stays with you.
The only real mistake is waiting while more time, more income, and more opportunity continue to slip through a structure that was never designed to preserve what you build.
So the question is simple:
How much longer are you willing to let delay cost more than the decision itself?
The most expensive sentence in the public system:
"I'll look into this later."
If you're earning $500,000 per year and unnecessarily overpaying the equivalent of $240/day into a system that is actively building tools to control you, then every month you delay this decision costs you roughly $7,200 — before you even factor in the freedom you can't get back.
In that context, a one‑time investment of $197 to evaluate the private door is not a risk. It is an ethical obligation to your future self and to your children.

The PFO Blueprint™ & Assessment
On this 1:1 Implementation call, you will:
1:1 call with Wayne Jr
Access to the PFO Boardroom Community — plus on-demand, instant access to community resources
Real scenario mapping across W-2, business owner, and investor profiles
The IRS code provision most CPAs have never read — shown in plain English
$197 credited toward your build when you move forward with implementation
Today - $197
One-time payment. Instant digital access. No subscription. No hidden fees.
Even if you never spend another dollar, you will walk away understanding more about how your financial life is actually structured than your CPA, your financial advisor, and your estate attorney have shown you combined.
Your $197 is credited toward implementation if you choose to move forward.

Copyright © 2026 - GetYourPFO.com | All Rights Reserved | Terms/Conditions/Privacy
Disclaimer: This site is not a part of the Google/Facebook/LinkedIn website or Google/Facebook Inc/LinkedIn. Additionally, this site NOT endorsed by Google/Facebook/LinkedIn in any way. GOOGLE/FACEBOOK/LinkedIn is a trademark of GOOGLE/FACEBOOK, Inc/LinkedIn. All mention of month
Please Read This Disclaimer Before Proceeding
Let me be totally transparent with you: the results I’m sharing with you are not typical. I’m not implying or guaranteeing that you’ll replicate them. The truth is, most people who buy "how-to" programs or information products don’t take the required action to get any results at all. That's why this isn't a "how-to" situation. This is a "let's do" opportunity. With that being said, I’ve been practicing direct response marketing and advertising for over 12 years, and I’ve worked hard to get here. That’s a huge part of why I’m able to get the results I do. Your results will depend on many factors including your experience, work ethic, skills, and how much effort you put in. Success in business requires risk and massive, consistent action. If you’re not willing to put in that effort or assume some risk, this program is not for you. If, however, you're ready to commit fully to your success and take action on the proven strategies inside, then you're in the right place.